Many business owners insure because they’ve been told to for years. Maybe a lender required it when you started, a client needed proof of insurance, or you started way back when in your career and have just never stopped. The problem is that what you’re insuring now might not fit your risk profile.
Insurance isn’t a stack of policies that you file away and forget. It’s coverage that’s built around the work your crews are performing and the projects in your book this year. Gaps and/or overlaps mean you’re either paying for coverage you’ll never use, or leaving an unknown gap you won’t know about until you file a claim.
Here’s how to compare what your business insurance already provides vs. what your operation needs right now.
Why Construction Insurance Looks Different From General Business Insurance
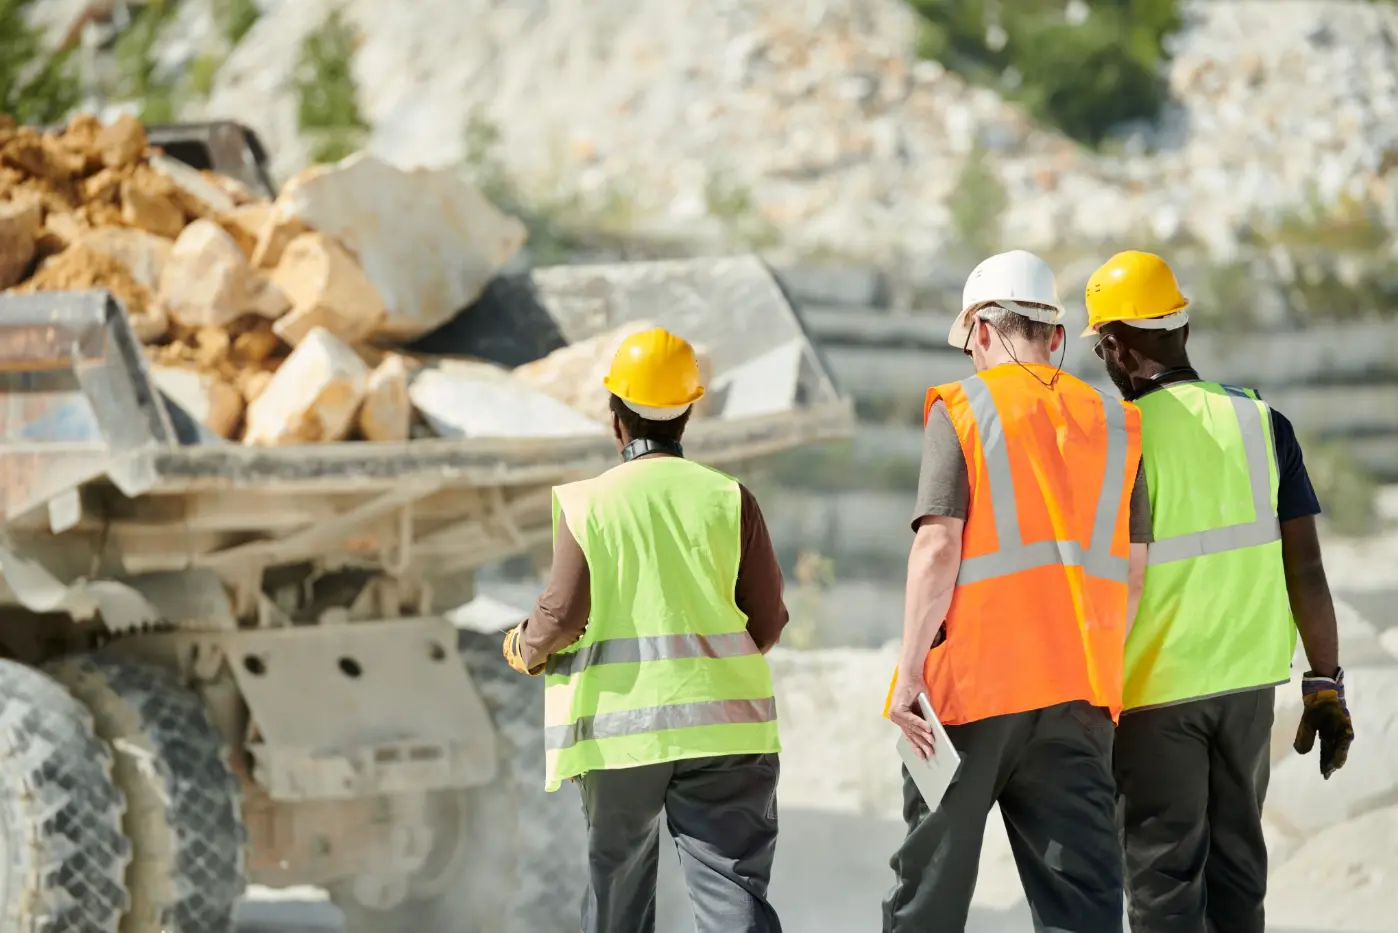
An office stays in one place year after year. A retail shop serves the same community, behind the same door, for as long as it’s open. Construction does not work that way. Job sites change from project to project, crews move between locations, and the value of the work in progress shifts as a project moves forward, sometimes week to week.
Construction business insurance has to flex with the work itself. That means accounting for tools and equipment moving between sites, subcontractors coming and going, and the property itself, which stays unfinished and exposed until the very last day of the job.
A general insurance policy built for one fixed location does not account for any of that movement, which is exactly why it falls short here.
Course of Construction Insurance and Why It Matters
Course of construction insurance, sometimes called builder’s risk, covers a project while it’s actively being built. It responds to fire, storm damage, theft of materials, and other losses that happen before the building is finished and occupied. It’s not something you can add after the fact and expect it to help.
This coverage often gets treated as an afterthought, tacked on late or skipped entirely on smaller jobs. But home construction insurance gaps during the build phase can turn a minor setback into a major cost, especially on projects with long timelines or expensive materials sitting on site.
What Should Sit Inside Your Insurance Program
A construction insurance program usually includes general liability, workers’ compensation, commercial auto, and property coverage as the core layers. Depending on the work you take on, it may also include equipment coverage, pollution liability, or professional liability for design work.
Insurance programs for construction firms should also include excess or umbrella coverage. Think of this layer as the backstop that sits above your other policies and responds when a large claim pushes past the limits of your general insurance.
Reviewing Insurance Line by Line
Start by listing every policy you carry, its limits, and its renewal date. Just that exercise alone gives you a clearer picture of your current insurance program before you even compare it against your actual operations and contract requirements.
Next, check each policy against the work you do now, not the work you did when the policy was first written. A business that has grown, added trades, or taken on bigger projects often outgrows its original coverage, and nobody notices until it matters.
Construction Insurance Cost and Where the Money Goes
Construction insurance cost depends on payroll, revenue, claims history, and the type of work performed. Firms doing higher-risk trades, like roofing or excavation, generally see higher premiums than firms doing lower-risk interior work.
Cutting corners on insurance to save money often backfires. A gap in coverage can cost far more than the premium saved, especially if a claim happens on a project where a client or lender expected certain protections to be in place.
Signs You Need to Check Your Insurance Information
If you have not looked at your insurance information in more than a year, take that as a sign. Check your insurance status against your current contracts. Many construction contracts spell out required limits now, and those requirements can shift from job to job without much warning.
Ask yourself a few questions.
- Has your revenue grown?
- Have you added new trades or equipment?
- Are you working in new states?
Any one of these can shift what your insurance program should look like.
Your insurance information should live somewhere you can find it fast, not buried three folders deep in an old email. Keep copies of every policy, certificate, and renewal date in one place, so a contract request does not turn into a last-minute scramble.
Comparing Insurance Quotes the Right Way
Shopping for insurance quotes feels like the natural first step, and it usually is. But price alone tells you very little. The best insurance for your business is not always the cheapest insurance option on the table. A low premium can mean thin limits or quiet exclusions that only show up after a loss, when it is too late to fix them.
If you just type “I need insurance” into a search bar, the search will return general insurance options, the kind that could apply to almost any business under the sun. Construction firms require more than that. You need to match coverage to your existing projects, not find an agency down the street.
How to Get Insurance That Fits Your Business
When you get insurance for a construction business, work with an agency that understands the industry itself, not just the paperwork behind it. An insurance agency that regularly places construction insurance will ask better questions about your projects and your crews, and those questions matter more than they seem to at first.
Our team can review your current policies and help you compare your insurance program against your business insurance needs today, not the needs you had when you first started the company.
Working With an Insurance Agency That Knows Construction
Finding the right insurance agency matters just as much as finding the right coverage. Starkweather & Shepley has worked with construction firms since 1879 and has stayed privately held, which means our advisors build long-term relationships instead of chasing one-time sales.
If you want help comparing what you have against what your business needs, reach out to our team for a straightforward review of your program, your limits, and your renewal dates.
Sources
- Insurance Information Institute (2026) Commercial general liability insurance. Available at: https://www.iii.org/article/commercial-general-liability-insurance (Accessed 9 September 2026).
- Investopedia (n.d.) Commercial General Liability (CGL) Insurance. Available at: https://www.investopedia.com/terms/c/commercial-general-liability-cgl.asp (Accessed 9 September 2026).